

The market is doing its favorite thing: moving in a direction that causes severe pain for most market participants.
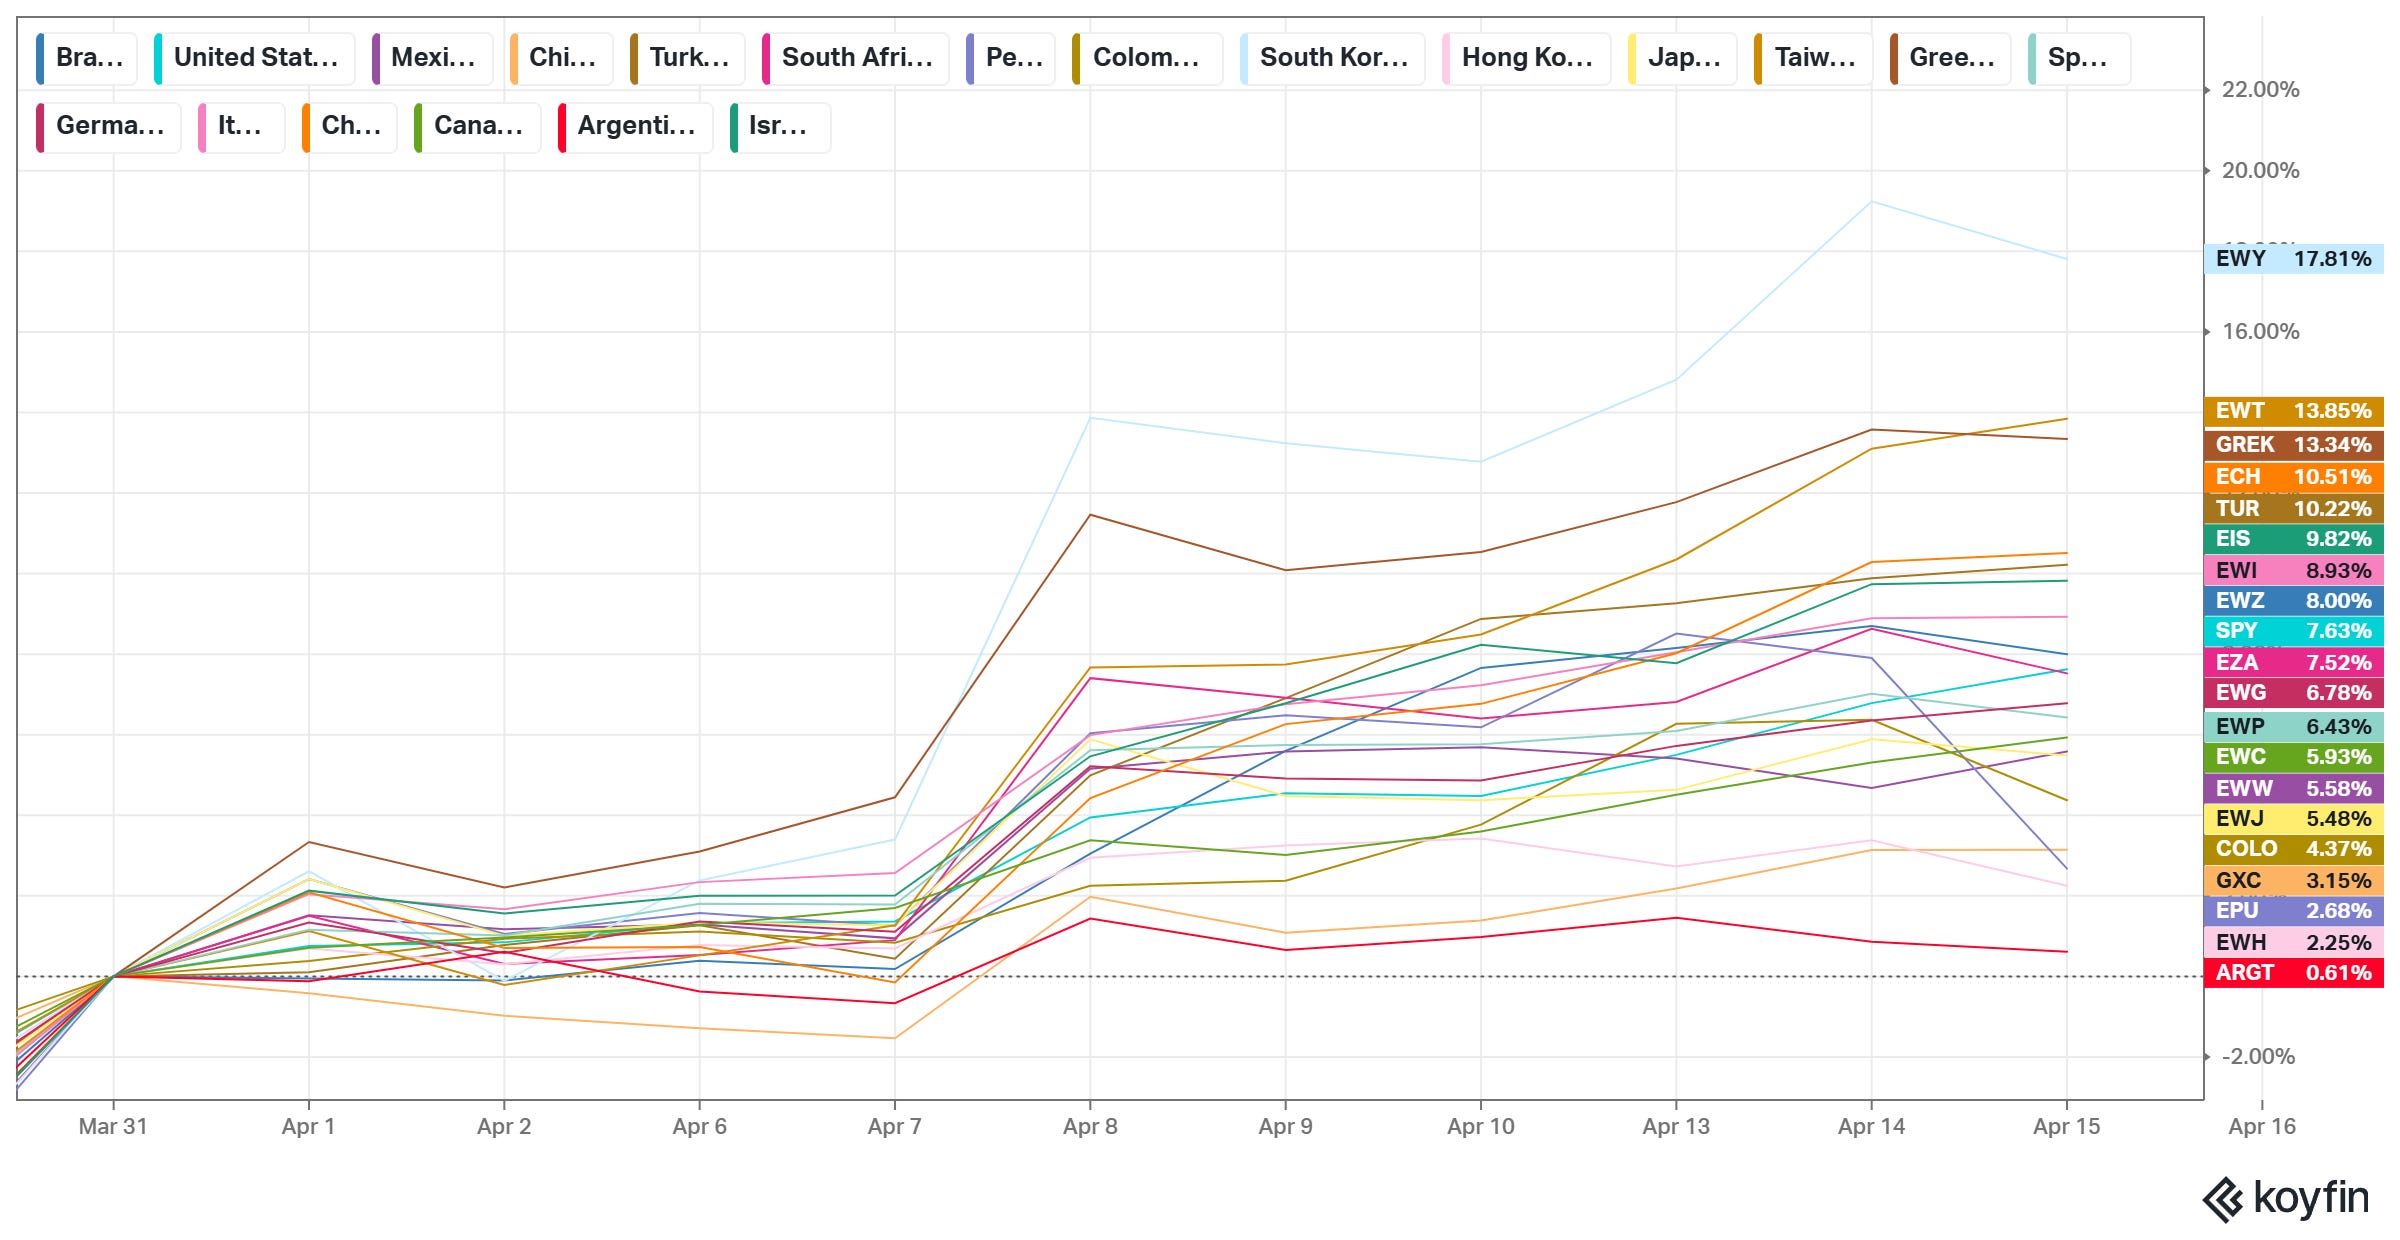
SPY is at ATH amid generational geoeconomic turmoil. But the bullish mood is not limited to US large caps. This week, non-US markets match the positive vibe, led by South Korea (NYSE: EWY), Taiwan (NYSE: EWT), and Greece (NYSE: GREK). LatAm equities are among the top performers, too. Chile (NYSE: ECH) and Brazil (NYSE: EWZ) are leading. For reference, look at the MTD chart below:
This market doesn’t make sense because shifting fundamentals matter, and the most obvious one is the Middle East crisis. Hence, the market is wrong, and am I right, isn’t it?
This is LatAm monthly intel but with a philosophical touch. Today, I inquire about flexibility, humility, and the LatAm energy space.
The line “The market doesn’t make sense…I am right, and the market is wrong,” is one of the most insidious fallacies in investing. Never fall for that. When inspired to claim “The market doesn’t make sense….,” refer to the following masterpiece:
The market is always right and doesn’t give a damn about your, mine, or anyone’s opinion. This was the short, emotional rant. Now the long and level-headed one.
The recent market behavior reminds me of a few axioms of prudent investing:
Your (and of course mine) market view is wrong until proven otherwise. The market is not the court, where you are innocent until proven otherwise.
Keep strong convictions weakly held. For example, I hold a conviction that the global economy is in the middle of a phase transition that will probably end badly. Nevertheless, I maintain mental flexibility. This means I happily initiate and hold long positions despite my bearish stance.
The difference between market and fundamentals is the same as the difference between map and territory. In investing, we too often play the map and ignore the territory, and on top of that, we get rewarded for it. In the long term, the territory (fundamentals) is the primary factor, and the map (market) is secondary. But the adjective long could be way longer than we are emotionally and financially able to hold our view. This is a pretentious way to say: the market can stay irrational longer than you can stay solvent. That’s why you must know what you are playing, a map or a territory.
The market is always right because every price reflects instantaneous consensus between sellers and buyers. Whatever the price of SPY or any other asset, even at its ATH/ATL, it is the right price. Period. This is intellectual humility in play, one of the most undervalued qualities of prudent investing.
In investing, doing the right thing is not the same as being right. The opportunity to make money lies in the gap between the future and current consensus prices. However, our estimates will frequently not match the realized consensus. Then, when you lose, who is right and who is wrong? Of course, the market is right, and you are wrong. When you win, you are not wrong, but you are not right per se. You won because you did the right thing – you showed up at the right price at the right moment – but not because you were right. What happened is that the market is right as usual, and you won because you agreed with him in advance.
Mental flexibility and intellectual humility are your best friends in any market regime.
This rant is a reality check and a reminder to myself not to fall into the luring trap of “The market doesn’t make sense…”
Now, let’s move on to LatAm.
First, how have LatAm equities fared since the beginning of the year?
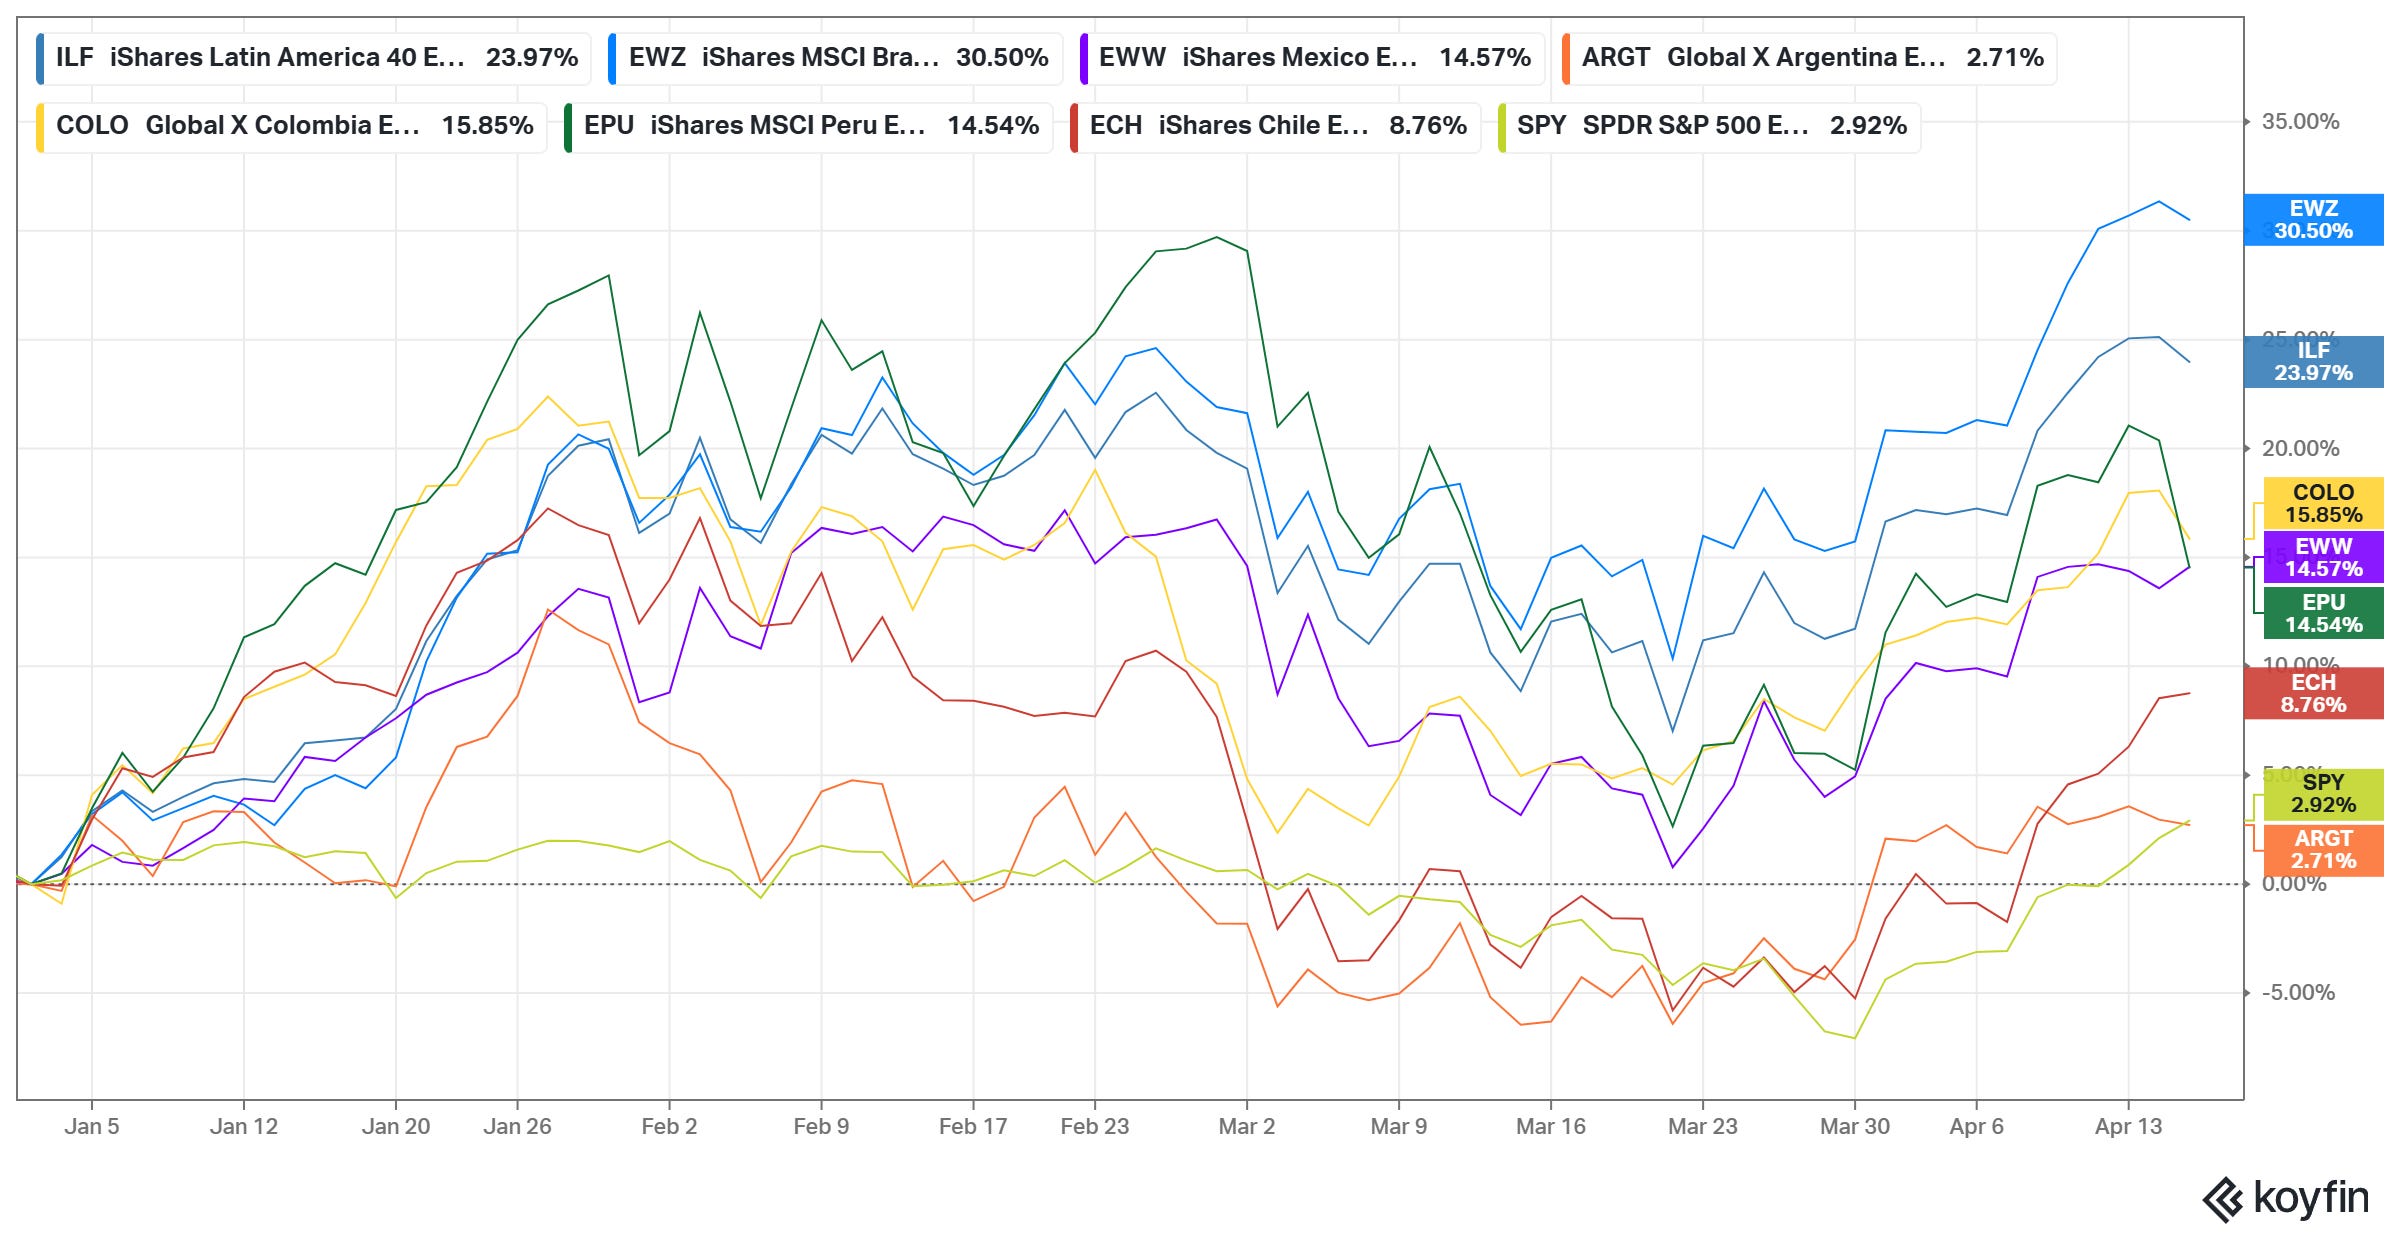
The YTD winner is Brazil, with an impressive 30.5% YTD gains. Colombia comes second with 15.85% YTD gains. Chile (NYSE: ECH) and Argentina (NYSE: ARGT) are the laggards.
It seems illogical, doesn’t it? Milei’s reforms are improving the Argentine economy, while Chile is expected to benefit from rising copper prices and the newly elected right-wing president.
The market discounts the future, not the present. What propelled Argie equities in the 2023-2024 period was the expectations that Javier Milei would initiate long-awaited change. Milei won the 2023 elections, and he delivered on his promises. But now in 2026, this is priced in, and the bull market has stalled. I wager Chile is in a similar position, in expectation context, of course, not (hyper)inflation one. The 2025 presidential elections were the catalysts that gave expectations for political change a deadline. Mr. Market reacted accordingly, and Chile was among the best-performing LatAm markets of 2025. Then, in December, Jose Antonio Kast won. So, it is all priced in, and the bull trend decelerated.
What is the conclusion: don’t touch Chile and Argentina?
This is the wrong question. Let’s frame it differently.
Which LatAm market offers cheap probability and excess asymmetry?
Argentina and Chile are out because asymmetry has been consumed to a large degree. Next in line are Brazil and Colombia. Presidential elections, potent catalysts, are still months away. Colombia holds elections on 31 May and Brazil on October 04.
To make things more interesting, LatAm energy names still offer cheap probability and excess asymmetry, and this is true not only for Brazil and Colombia but also for Argentina. To underline, the leading factor here is the changing energy landscape, with the country’s internal dynamics (election cycle and interest rate changes) as secondary and tertiary drivers.
Let’s dig deeper.
Six weeks of Brent above $90/bbl have delivered the most favorable pricing environment for LatAm oil producers since the post-Ukraine invasion spike of 2022. But unlike 2022, this time the continent’s exporters are in fundamentally different positions, and the companies carry sharply divergent risk-reward profiles.
But why Latin American barrels matter more than ever?
The Hormuz crisis has removed roughly 5-6 million bbl/day (Hormuz’s crude oil flow rate of 15 million bbl/day minus G7’s SPR releases, OECD’s commercial reserves, and Gulf States’ bypass pipelines capacity) of crude from the global market. Asian refiners, who previously relied on short-haul Middle Eastern grades, are now scrambling for Atlantic Basin crude. Brazilian pre-salt medium-sour crude, Colombian heavy blends, and Argentine Vaca Muerta light crude are all suddenly in higher demand.
But the thing is, LatAm NOCs and IOCs were well-positioned even before the Middle East crisis. The YTD price action is proof of that. Since the beginning of 2026, LatAm energy has been on the move:
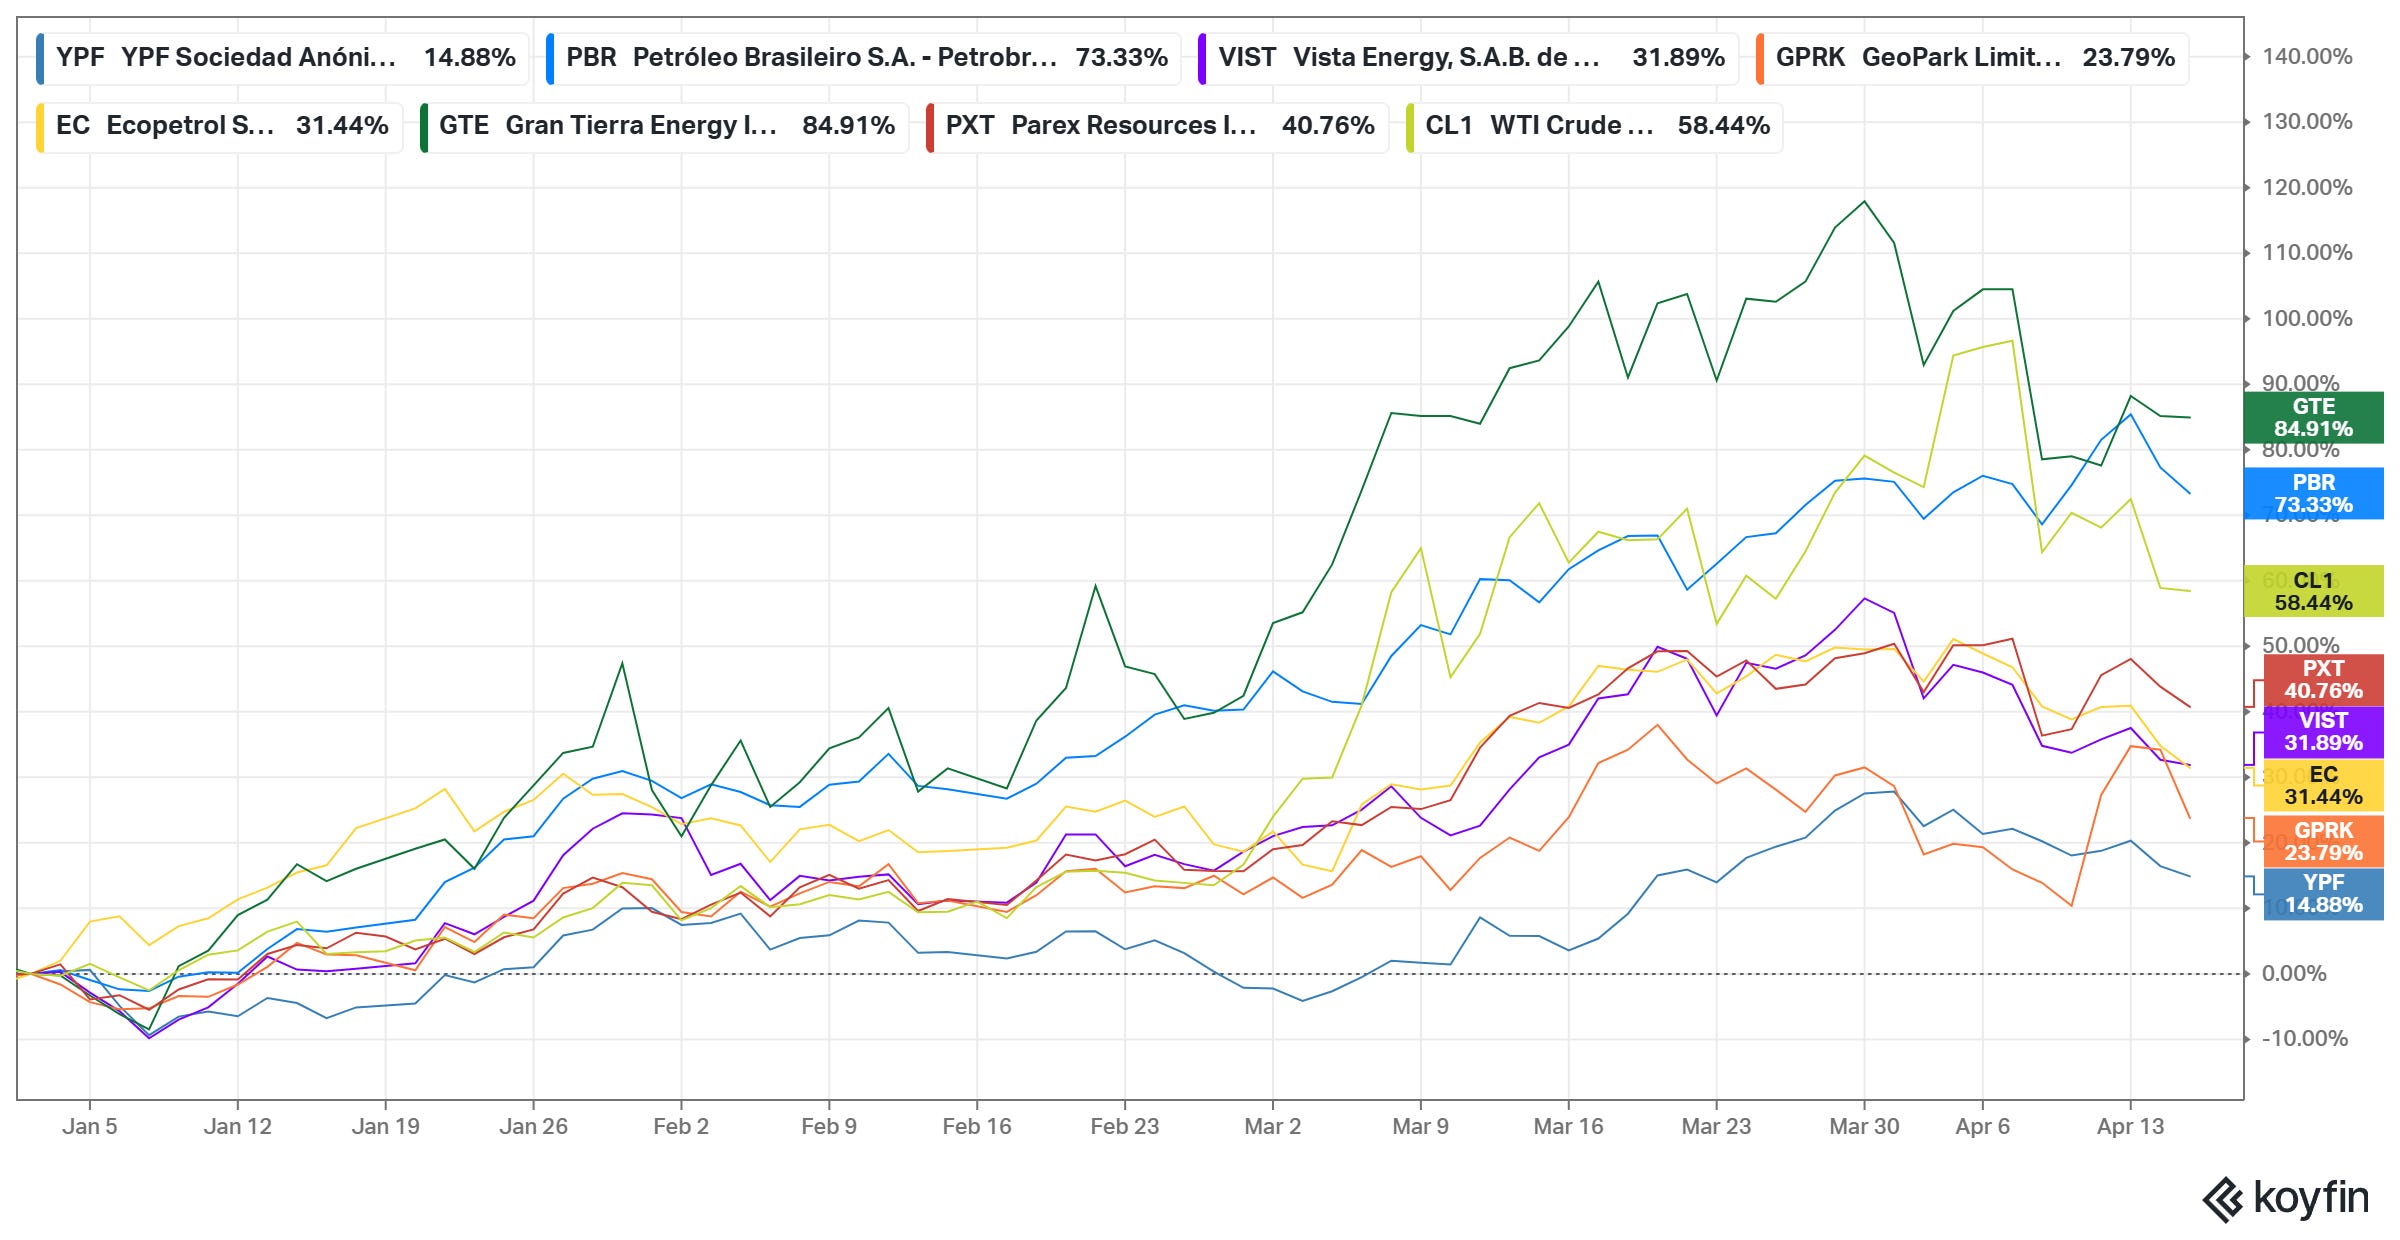
As the chart above shows, the bullish move began well before the “Epic Fury” operation. The war simply accelerated the ongoing trend.
Then, where to look for opportunities?
Brazil and Petrobras
Brazil’s pre-salt fields produce roughly 3.8 million barrels per day of high-quality crude, with lifting costs of $6–7 per barrel, among the lowest in the world. At >$90/bbl Brent, Petrobras (NYSE: PBR) is generating enormous free cash flow from its upstream operations.
For the curious readers, I covered Petrobras in December 2025:

But the company is simultaneously being weaponized as an inflation shield. Petrobras sells gasoline and diesel domestically at roughly 60% of international prices, absorbing the “defasagem” (subsidy gap) that widens as each dollar of Brent rises. The fiscal bleed from importing refined products at $110/bbl and selling at the equivalent of $66/bbl is staggering, and it is compounded by real depreciation that makes dollar-denominated imports even more expensive.
For investors, Petrobras is a leveraged bet on two variables: robust oil prices and the Brazilian government’s willingness to allow domestic prices to rise. If Brasilia eventually capitulates and raises pump prices, as it always has historically, Petrobras captures the full Brent upside plus the repricing of domestic fuel margins. If the government holds prices artificially low through the 2026 election cycle, the upstream windfall is reduced by downstream subsidy losses, and the dividend could be at risk. I wager that the company’s Q1 2026 earnings (reporting date: May 11) will be the most-watched filing in the EM energy space this quarter.
Colombia, Ecopetrol, and Independents
Ecopetrol (NYSE: EC) produces roughly 750,000 bbl/day, the majority heavy crude sold at a discount to Brent but still tracking its moves. With Brent above $90/bbl, even Castilla and Vasconia blends are generating substantial cash. Ecopetrol’s 2025 proved reserves of 1,944 million barrels of oil equivalent, with a replacement ratio of 121%, provide a decent runway.
But there is a persistent political problem. Colombia’s production has been declining because of the Petro government’s hostility toward new exploration licensing, which has frozen frontier development (for the new to Colombian energy space: Ecopetrol is 88.49% state-owned). The good news is that the higher oil prices offset the impact of stalled production growth. A $10/bbl increase in Brent adds roughly $800 million to annual EBITDA, but the incremental dollars will not be reinvested in growth because the excess cash will plug Colombia’s fiscal gap.
For the smaller Colombian-exposed independents, Gran Tierra Energy (NYSE: GTE) and Parex Resources (TSX: PXT), the calculus is simpler. Both are pure-play Colombian producers with breakeven costs well below current prices. Gran Tierra’s Middle Magdalena and Putumayo operations generate outsized free cash flow at Brent prices above $90/bbl. The company trades at roughly an 18% FCF yield, making GTE one of the cheapest names in the E&P universe. Parex, focused on the Llanos Basin, has a fortress balance sheet (for reference, 0.1 Total Debt to EBITDA ratio), a buyback program, and a production base that prints cash at these prices. Both companies benefit from the price without carrying the political burden that weighs on Ecopetrol.
GeoPark (NYSE: GPRK) adds geographic diversification with operations across Colombia and Argentina. Its Colombian production (~35,000 bbl/d) benefits from the Brent spike. However, GPRK’s cost structure is somewhat higher than Parex or Gran Tierra, and its Ecuador exposure introduces additional country risk in a region where governments are tempted to raise extraction taxes during price windfalls.
Argentina, YPF, and Vista
Argentina is a compelling story in the energy context. The Vaca Muerta shale formation, with an estimated breakeven of $36–45 per barrel, is profitable at any price above $45/bbl and prints extraordinary returns at >$90/bbl. The formation produces light crude grading 38–42° API, which commands a premium over heavier Latin American grades (particularly Colombian and Venezuelan sorts), and production is growing 30% year-on-year, with output surpassing 500,000 barrels per day.
YPF (NYSE: YPF) is leading the charge. The company plans to spend $5.6 billion in 2026, with 80% directed to upstream Vaca Muerta development. The VMOS pipeline project (Vaca Muerta Oil Sur), a $3 billion consortium investment to build 550,000 barrels per day of takeaway capacity to the Atlantic coast export terminal at Punta Colorada, is now the most strategically important midstream project in the Western Hemisphere. At >$90/bbl Brent and a $36–45 breakeven, YPF’s netback per barrel is extraordinary, a roughly >$45/bbl. The Milei government’s RIGI incentive regime is accelerating foreign investment, and the crisis is proving in real time that non-Hormuz, non-OPEC supply carries a geopolitical premium that Vaca Muerta can capture permanently.
Vista Energy (NYSE: VIST) is the pure-play Vaca Muerta vehicle, free of YPF’s state-ownership complexity. Vista’s Bajada del Palo Oeste block is delivering some of the highest well productivities in the formation, with single-well EURs (Estimated Ultimate Recovery) that rival, and in some cases exceed, the best Permian wells. The company has guided to 80,000+ bbl/day by 2026, growing at 20%+ annually, with all-in sustaining costs around $20/bbl. At $90 Brent, Vista is generating free cash flow yields above 15%, a level typically reserved for distressed assets, not a company growing production at double-digit rates in one of the world’s best shale formations.
The last few months were dedicated to Latin America. Here is a list of my recent articles covering LatAm as an investing opportunity from different angles.


PS: For more actionable and asymmetric ideas on LatAm and beyond, consider TheOldEconomy premium plans: Researcher and Strategist.
Thank you for being part of TheOldEconomy. Here’s to your continued growth and success, one wise decision at a time.
Invest wisely,
Mihail Stoyanov
Founder, TheOldEconomy
Everything described on this site, TheOldEconomy.substack.com, has been created for educational purposes only. It does not constitute advice, recommendation, or counsel for investing in securities.
The opinions expressed in such publications are those of the author and are subject to change without notice. You are advised to do your own research and discuss your investments with financial advisers to understand whether any investment suits your needs and goals.
Thanks for the analysis of Latam E&Ps. Just for precision, Gran Tierra, not Geopark, is exposed to Ecuador. The couple of assets that Geopark had there were acquired by GT last year.